
Smart steps for personal finance: a practical loans.edu.pl guide
A practical, checklist-style guide to personal finance essentials, with actionable steps on loans, investing, banking and how local US job listings can affect y

If you want to manage money confidently, you need clear steps you can apply now. This guide translates everyday finance decisions into concrete actions you can take—without hype or guesswork. You’ll see how basic budgeting, loan choices, and career resources like local job listings in the USA can all align to improve your financial outlook.
The pieces below build from fundamentals to practical options, showing real-world examples and guardrails. Expect tips you can implement this week, from evaluating loan terms to planning for irregular income. The aim is to help you make smarter money choices with every paycheck.
By the end you’ll have a repeatable checklist you can reuse as your life or goals change, keeping debt under control and building toward real financial stability.
- Plan your monthly budget to control debt and build savings.
- Compare loan offers by true cost, not advertised payments.
- Build credit steadily with small, regular applications and careful banking.
- Balance savings with safe investing to grow wealth over time.
Foundations and budgeting
Assess your income and debt
Start by listing monthly income sources and fixed expenses. This gives you a clear picture of how much you can safely allocate to debt payoff and savings. Use a simple spreadsheet or mobile app to track ratios over 90 days, and adjust as income changes. local job listings in the USA
Next, identify high-interest debt and prioritize it in your plan. Paying down costly balances first can free up cash for savings and investments, even if the total debt seems large.
Track progress monthly and reset goals as needed.
- List all income streams and fixed costs
- Calculate debt-to-income ratio
- Target one debt payoff priority
- Set a realistic monthly savings goal
- Review budget weekly
Emergency fund and basics
An emergency fund acts as a financial buffer. Start with a small, attainable target and build toward three to six months of essential expenses as your confidence grows.
Keep this fund in a liquid account so you can access it quickly if irregular income or unexpected costs arise. Avoid placing it in high-risk investments that could lose value when you need it.
Tracking progress is key; treat this fund as a fixed monthly payment until you reach your goal.
- Choose a liquid savings vehicle
- Set a time-bound savings target
- Automate monthly transfers
- Reassess fund size after major life changes
- Avoid risky investments for this money
Understanding loans and terms
Types of loans and when to pick them
There are several loan types, each with different repayment terms and costs. Personal loans can fix cash gaps, while secured loans use collateral that may lower interest but introduces risk to assets. A useful resource on this topic: Defense News US headlines.
When choosing, compare APRs, fees, and payoff timelines rather than advertised monthly payments. A longer term lowers monthly costs but increases total interest.
Use a simple comparison sheet to isolate the impact of each term on total cost over time.
- Compare APR, fees, and total cost
- Note collateral requirements
- Estimate true monthly payments
- Assess payoff timeline and flexibility
- Keep lender communication open
Credit score and loan access
Your credit score affects loan approval chances and interest rates. A few points can influence the terms you receive, so it pays to understand what helps and what doesn’t.
Try to keep credit utilization low and avoid applying for multiple loans in a short window, which can temporarily lower scores.
Monitor your credit report for errors and correct them promptly to avoid unnecessary rate hikes.
- Maintain low credit utilization
- Limit loan applications
- Check credit reports regularly
- Dispute inaccuracies promptly
- Prefer prequalification checks over hard pulls
Credit-building paths and banking options
Saving vs. investing for beginners
Begin with a savings habit that builds discipline. Once you have a cushion, you can consider low-risk investments aligned with your goals and time horizon. A useful resource on this topic: advertise your event in the USA.
Diversify slowly; even small, regular contributions help compound over time. Use automation to keep consistency without constant manual effort.
Evaluate risk tolerance and timeline before choosing funds or accounts. Short-term needs require more liquidity than long-term growth.
- Set a monthly contribution
- Choose a simple, diversified fund
- Automate transfers
- Rebalance annually
- Review risk tolerance
| Option | Fees and costs | Liquidity and risk |
|---|---|---|
| Savings account | Low fees | High liquidity |
| Balanced index fund | Moderate fees | Moderate risk |
| Cash emergency fund | No risk, tiny return | Very high liquidity |
Banking that fits your routine
Select a bank or credit union with accessible customer service, reasonable fees, and convenient app features. Look for features like budgeting tools and instant transfers that save time.
Understand debit and credit features, overdraft protections, and how ATM networks affect costs. Small choices there accumulate over time.
Keep a record of monthly banking costs to spot hidden fees and adjust accounts if needed.
- Compare features beyond ATM access
- Evaluate monthly fees
- Test customer support responsiveness
- Track total banking costs
- Plan for overdraft protections
Consider how changes in income could affect ability to repay and plan a fallback.
Various routes to funding and risk awareness
Alternative funding options
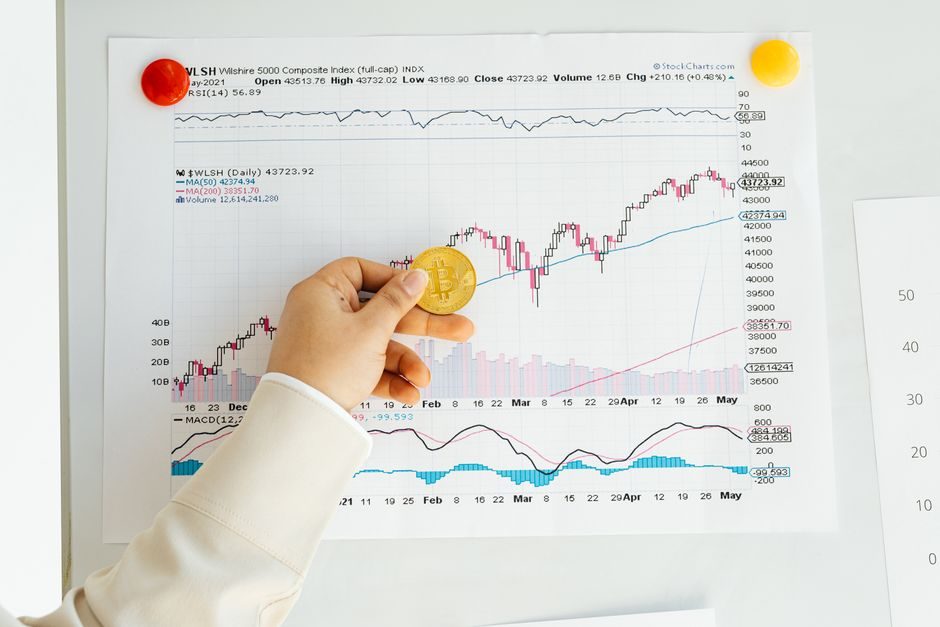
Explore options beyond traditional loans, such as peer-to-peer platforms or credit-builder products. These can help if you’re building credit or facing a temporary cash gap. A useful resource on this topic: local business directory in the USA.
Each option carries distinct costs and terms. Read the fine print on repayment schedules and penalties before committing.
Consider how changes in income could affect ability to repay and plan a fallback.
- Research repayment terms
- Check penalties and fees
- Assess impact on credit score
- Match to income stability
- Have a backup plan
Risks of leverage and crypto
Leverage and volatile assets can amplify gains but also losses. Only allocate what you can afford to lose and avoid chasing rapid profits.
Stay informed about regulatory changes and fees that can alter liquidity or access to funds.
Keep separate, clearly labeled accounts for speculative assets and essential funds.
- Limit exposure to volatile assets
- Set stop-loss or exit rules
- Keep liquidity separate
- Review regulatory changes impacting crypto
- Avoid high-risk speculative bets
Budgeting for life changes
Adjusting monthly budgets
Start with a mid-month check-in to measure spend against goals. Track categories like housing, food, and transport for two weeks before adjusting. Use a simple calendar to anticipate expected changes, such as a move or a salary shift. publish a death notice in the USA
- Identify predicted costs tied to the change.
- Cut nonessential expenses first.
- Revisit emergency fund target after the change
Next, reallocate funds from flexible categories to essential needs. If rent rises, trim discretionary spending or renegotiate utilities. Document changes in a single note so you can review trends over the next 30 days.
Finally, set a concrete limit for nonessential purchases and adhere to it. This helps maintain stability during transitions and protects savings. A clear rule reduces impulse buys and keeps debt under control.
- Set a 5% or $50 buffer for unexpected bills
- Adjust auto-pay dates to avoid late fees
- Create a 30-day expense watchlist
- Use cash envelopes for groceries and entertainment
- Review insurance coverage after a life change
Investing for different goals
Tailored goal timelines
Define each goal with a clear timeframe, such as five years for a house fund or ten years for retirement. This helps determine risk tolerance and asset allocation. Use a simple calculator to estimate how much you need monthly.
- Set 2–3 goals with clear deadlines.
- Choose appropriate accounts and funds.
- Schedule automatic transfers from paycheck.
- Review progress and adjust annually
Different goals deserve different tools: a high-yield savings account for short-term needs, a diversified ETF or index fund for long horizons. Automate contributions to keep consistency and bypass decision fatigue. Review progress quarterly.
Track milestone progress and rebalance when needed. If one goal overshoots, shift some funds to longer-term strategies or increase savings for another target. Stay disciplined to avoid chasing short-term gains.
- Short-term goal: keep capital safe
- Medium-term goal: blend growth and stability
- Long-term goal: focus on growth with risk controls
- Automate contributions to avoid gaps
- Rebalance at least once a year
Protecting your assets
Safeguard essentials first
List essential assets: home, health, income, and retirement accounts. Prioritize protections that prevent catastrophic losses and keep daily life stable. Start with a baseline plan that covers emergencies without overpaying.
- ☐ List essential protections you lack
- ☐ Estimate the impact of a loss
- ☐ Set annual review reminders
Then add layers: disability insurance, umbrella liability for high-risk households, and adequate health coverage. Compare plans by out-of-pocket costs and claim ease, not just monthly premiums. Small differences can matter under stress.
Finally, keep documents organized and updated. Store policies, beneficiary designations, and emergency contacts in one secure place. Review changes after major life events and at least once a year.
- Prioritize core protections first
- Choose plans by real costs, not headlines
- Keep a central, secure file of documents
- Update beneficiaries after major events
- Annual check of coverage sufficiency
Smart cash flow strategies
Automate and space out payments
Automate bills to avoid late fees and keep your credit intact. Schedule timing so fixed costs align with paydays, reducing the risk of overdrafts. This minimizes manual tracking while keeping liquidity steady.
Split irregular income into fixed and flexible buckets. A predictable base supports debt payments, while a variable portion grows savings or investments. This clarity reduces stress when earnings fluctuate.
Regularly review subscriptions and recurring charges. Cancel or downgrade unused services to free up cash for debt repayment or a savings target. Small cuts add up over several months.
- Automate all fixed payments
- Use a two-bucket approach for income
- Audit subscriptions quarterly
- Prioritize debt payoff with excess cash
- Keep a rolling 30-day expense plan
Frequently asked questions
What should I start with in personal finance?Begin with a clear snapshot of income and fixed costs, then identify an emergency fund target. Automate savings to build a safety net and reduce the likelihood of forgetting payments. As comfort grows, expand into retirement accounts and smart investing.
How can I manage debt effectively?List all debts by interest rate, then prioritize paying off the high-cost loans first. Maintain minimum payments on others while applying extra funds to the top priority. Regularly review terms and avoid new debt unless necessary.
Is local job data useful for finance planning?Yes. Local listings help you understand regional pay, benefits, and cost of living. Use that data to set realistic savings goals and adjust your budget if you relocate or take a different role.
When should I seek professional help?If your situation involves complex taxes, estate planning, or intricate investment strategies, a qualified advisor can tailor a plan. Ask about fees, scope, and timelines before committing.
Conclusion
Takeaways: begin with a practical budget, automate saving, and track progress to stay aligned with goals. Build a safety net before pursuing aggressive growth, and adjust plans as life changes.
Next step: draft a simple one-page plan for the next year that links income, debt payoff, and retirement contributions, then automate the related steps and check in monthly for progress.

Add Loans Guide as a preferred source on Google


