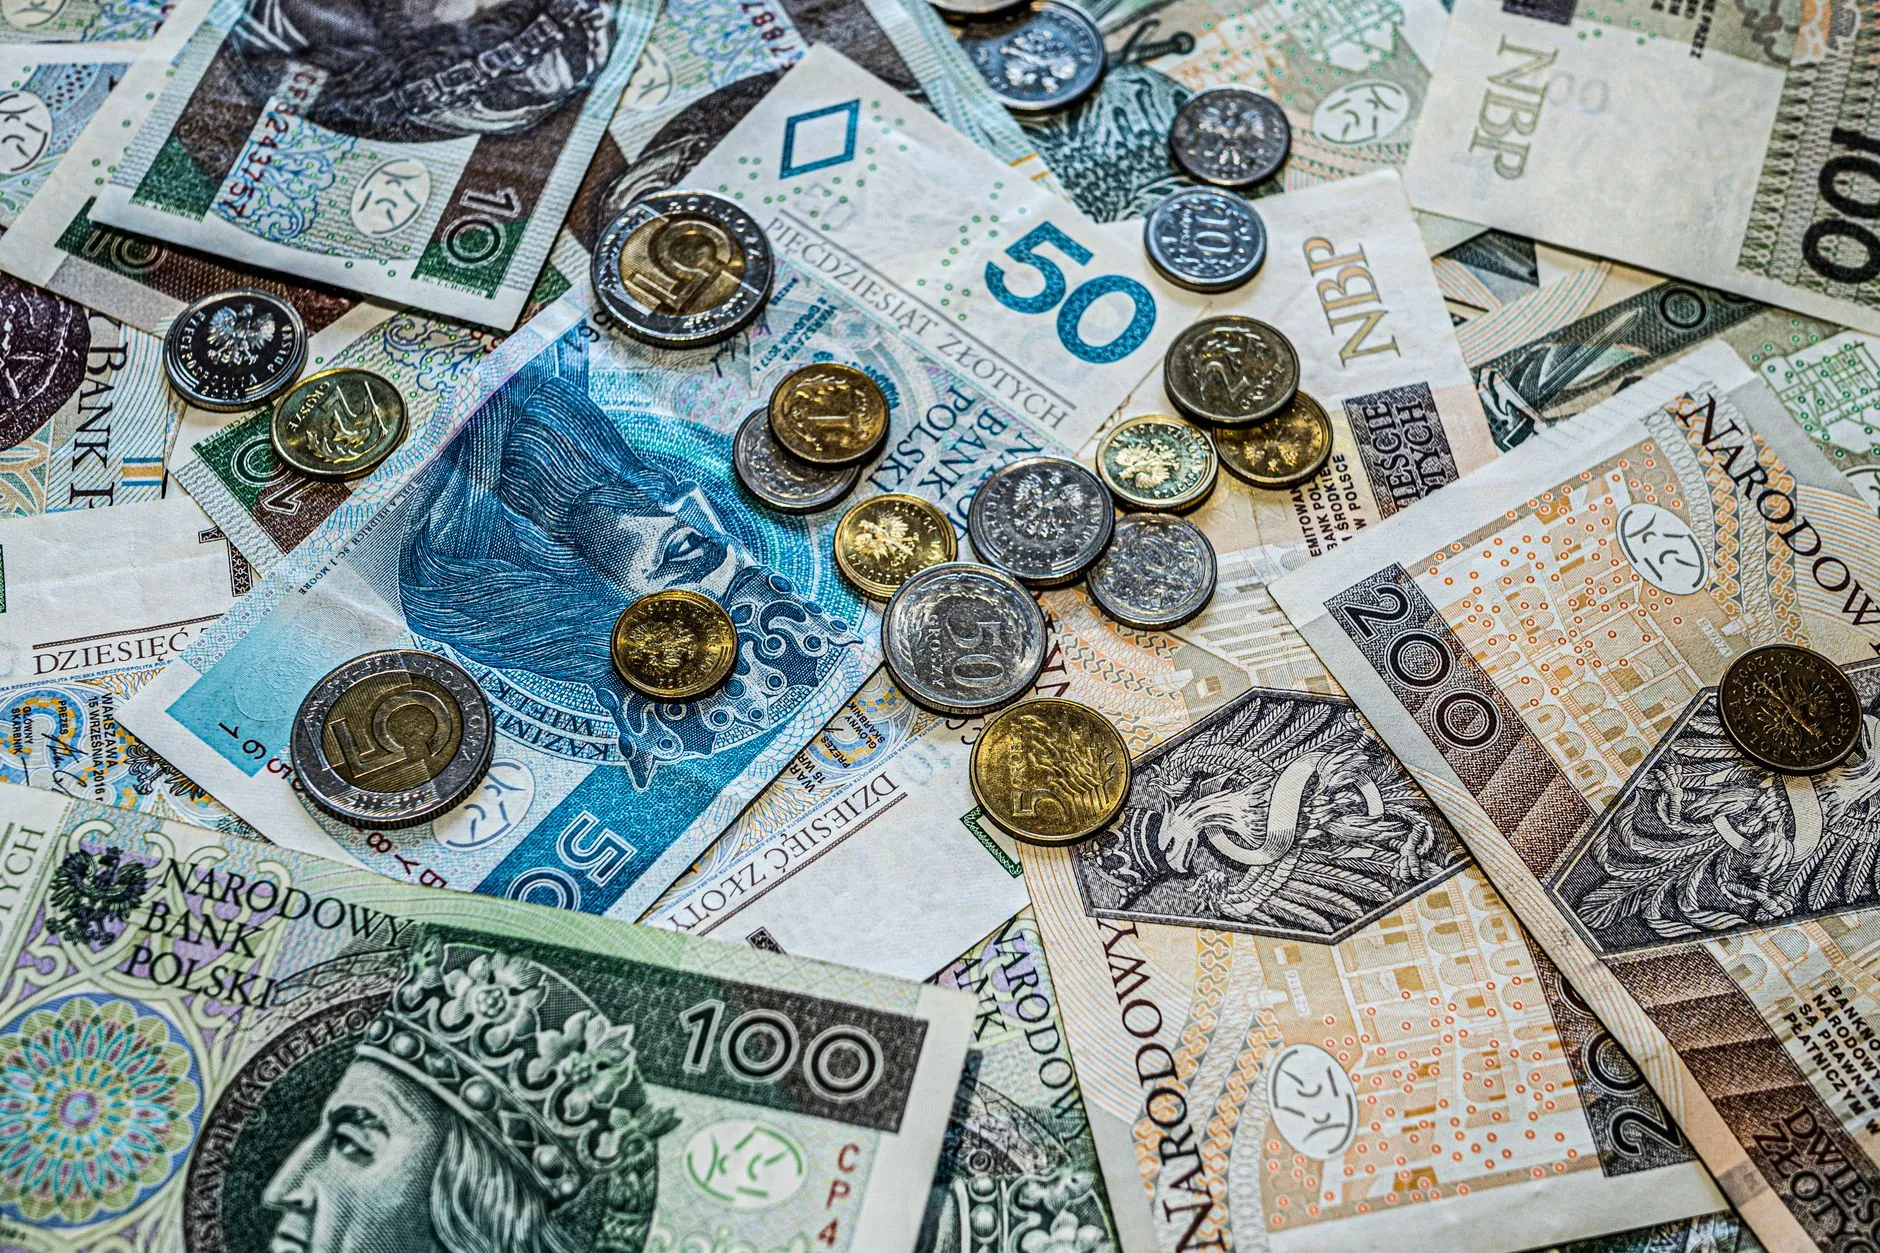
As the snow melts away in Poland’s vibrant cities, the annual cycle of financial planning is in full swing. For many, the first quarter of the year is a time for reflection on past financial decisions and a chance to set new goals for the future. Whether you’re looking to tackle high-interest loans, build a safety net, or make the most of your tax refunds, this is an opportune moment to take control of your finances. With the average Pole holding multiple bank accounts and credit cards, it’s not uncommon for individuals to feel overwhelmed by the complexity of it all. Yet, with the right approach, achieving financial freedom is within reach. Consider the home you’ve always dreamed of owning – perhaps you’ve been eyeing a cozy apartment in a desirable neighborhood. Before you start scouring home improvement websites, like home improvement ideas budget tips, to prepare for that down payment, it’s essential to get your financial house in order. Effective financial planning requires a strategic approach, and in this article, we’ll share 10 smart money moves to make before the end of Q1 in Poland to secure your financial future.
Ditch the Debt, Not Your Dreams: Tackling High-Interest Loans in Poland
In Poland, high-interest loans have become a pressing concern for many individuals. According to a report by the Polish Financial Supervision Authority, there are over 2.5 million citizens in the country struggling with excessive debt. High-interest loans can quickly snowball into a financial nightmare, making it challenging to recover and achieve financial freedom. In this section, we’ll discuss the importance of tackling high-interest loans and provide actionable tips to help you get back on track.
One key aspect to understand is that high-interest loans often come with exorbitant APRs, making it difficult to repay the principal amount. For instance, a 12-month loan of PLN 5,000 with an APR of 20% could result in a total repayment of over PLN 6,500. This is due to the compounding interest, which can quickly add up and lead to a vicious cycle of debt. To break this cycle, it’s essential to prioritize debt repayment and create a solid plan to tackle high-interest loans.
One effective way to do this is by consolidating your debt into a lower-interest loan or credit card. This can significantly reduce your monthly payments and interest costs, making it easier to stay on top of your finances. For example, consider transferring your high-interest loan balance to a credit card with a 0% introductory APR, which can save you hundreds of zlotys in interest charges. This allows you to focus on paying off the principal amount without worrying about the interest rate. By taking control of your debt and making informed financial decisions, you can achieve financial freedom and secure a brighter financial future.
A Hedge Against Uncertainty: Diversifying Your Investment Portfolio
A well-diversified investment portfolio is essential for mitigating risks and ensuring long-term financial stability. Diversification involves spreading investments across different asset classes, such as stocks, bonds, real estate, and commodities. This strategy helps reduce the impact of market fluctuations on individual investments, making it easier to weather economic downturns. For instance, if the stock market declines, a diversified portfolio can help cushion the losses by retaining value in other assets.
- Insufficient diversification: Many investors tend to put too much of their portfolio into a single asset class, such as stocks or real estate, which can leave them vulnerable to market fluctuations. A better approach is to allocate your investments across multiple asset classes, using a portion for each.
- Ignoring inflation: Failing to account for inflation can erode the purchasing power of returns, rendering them less effective. Consider incorporating inflation-indexed bonds or commodities into your portfolio to mitigate this risk.
- Not regular portfolio rebalancing: Failing to rebalance your portfolio regularly can lead to a drift away from your target asset allocation, exposing you to unnecessary risks. Schedule regular portfolio reviews and rebalancing to maintain your desired asset allocation.
It’s also important to consider the tax implications of your investments. For example, tax-efficient investing strategies, such as tax-loss harvesting, can help minimize taxes and maximize returns. Additionally, incorporating ESG (Environmental, Social, and Governance) considerations into your investment decisions can lead to both financial gains and societal benefits.
With these factors in mind, investors can create a well-rounded investment portfolio that balances risk and potential returns. By avoiding common mistakes and adopting a diversified, tax-efficient approach, individuals can achieve financial freedom and peace of mind.
Tax Refunds to Savings Accounts: Make Your Polish Złoty Work for You
Polish citizens often overlook the potential of tax refunds as a means to boost their savings. By filing tax returns, individuals can claim back any overpaid taxes and potentially receive a significant sum. This refund can then be deposited into a savings account, generating interest and growing over time. In fact, a dedicated savings account specifically designed for tax refunds can help maximize this opportunity. By keeping your refund separate from your main account, you’ll be less likely to spend it impulsively and more likely to let it grow steadily.
Moreover, it’s worth noting that tax refunds can be a valuable opportunity to invest in a low-risk asset, such as a high-yield savings account or a useful information daily tips on personal finance can provide a solid foundation for your financial decisions.
When to Splurge, When to Save: Budgeting for Q2 and Beyond in Poland
When to Splurge, When to Save: Budgeting for Q2 and Beyond in Poland
As we approach the end of Q1, it’s natural to reassess your financial priorities and make adjustments for the second quarter and beyond. A balanced approach to budgeting is crucial for achieving financial freedom. It’s essential to strike a balance between enjoying the fruits of your labor and saving for the future. This is where the concept of discretionary spending comes in. Discretionary spending refers to non-essential expenses that bring you joy or satisfaction, such as dining out, traveling, or hobbies.
| Budget Category | Average Polish Spending Habit | Recommended Allocation |
|---|---|---|
| Discretionary Spending | 40-50% of monthly income | 30-40% |
| Savings | 10-20% of monthly income | 20-30% |
| Debt Repayment | 5-10% of monthly income | 10-15% |
For instance, you may find that dining out is a significant part of your discretionary spending. A great way to reduce your expenses in this area is to cook at home more often, using recipes from reliable sources like Food.com. The Intersection of Faith and useful information daily tips can also provide valuable insights on how to balance your spiritual and financial well-being. By doing so, you can free up funds for more meaningful experiences and savings. In the next section, we will explore investment strategies to help you grow your wealth beyond Q2.”
From Emergency Fund to Long-Term Growth: Building a Safety Net for Financial Freedom
Building a safety net for financial freedom involves creating a secure foundation that can weather unexpected expenses, interest rate fluctuations, and market downturns. A well-structured emergency fund can provide peace of mind and help you avoid debt. For instance, a study by the Polish Bank Association showed that 75% of households in Poland have some savings, but a mere 25% have enough to cover three months of essential expenses. This highlights the need for a targeted savings strategy.
- ☐ Allocate 3-6 months’ worth of living expenses to your emergency fund
- ☐ Set up a high-yield savings account to earn passive income
- ☐ Pay off high-interest debt before investing in long-term growth
- ☐ Diversify your investments to minimize risk
Having a solid emergency fund in place, it’s essential to consider long-term growth opportunities. Investing in a tax-advantaged retirement account, such as a ZUS (polish pension scheme), can help you build wealth over time. As you plan for the future, you may also want to read The Evolution of Gaming: From, which offers valuable insights into the power of long-term progress. By combining a safety net with strategic investing, you’ll be well on your way to achieving financial freedom in Poland.”
The Q1 Line in the Sand
March 31 isn’t just another date on the calendar—it is a firm boundary line between passive planning and genuine wealth creation. Shifting capital into higher-yielding assets, clearing expensive high-interest loans, and making full use of local tax allowances aren’t chores to kick down the road. The choices executed before April sets the trajectory for your entire financial year in Poland.
Financial independence rarely stems from a single stroke of luck. It grows out of deliberate, repeatable habits—where seeking out useful information daily tips keeps your strategy sharp amidst shifting inflation figures and fluctuating bank rates. Take an honest look at your balances before the quarter officially wraps. Is your money actively working to secure your future, or is it sitting idle on the sidelines? The Q1 window is closing fast, but taking decisive control today ensures you won’t be playing catch-up come December.
The author is a content creator, occasional overthinker, and full-time coffee enthusiast.
For more insights on this topic, you might find Ürün İncelemeleri İçin En İyi İpucu particularly informative.
For more insights on this topic, you might find 10 Thrilling Travel Destinations for a particularly informative.
If you enjoyed this article, we recommend checking out Olimpiyat Oyunları İletişiminin Yeni Zeminleri: Trendler for further reading.