8 min read · Updated: 2026-10-05
If you’re weighing a loan, you need practical steps you can follow, not vague advice. This guide gives you a clear path from basics to options, highlighting where legal help matters and how to assess risk. You’ll learn when Avukat Ara can be useful, and how to verify advice without overpaying.
Loans can be judged by terms, fees, and timing. This article keeps the focus on what readers can do today: compare products, read the fine print, and plan for future payments.
The goal is a concise, actionable checklist you can reference before you sign anything or hire legal help. Follow the prompts, and you’ll move from uncertainty to a prepared, informed decision.
- Know how to compare loans beyond the monthly payment and identify the true cost.
- Ask questions about terms, fees, and prepayment to avoid surprises.
- Use a simple, repeatable process to evaluate offers and when to seek legal help.
- Prepare a written plan that covers budget, milestones, and risk management.
Basics of loans to know
Understanding loan terms
Knowing the difference between interest, principal, and fees helps you compare offers. Start with the annual percentage rate, then check any penalties for early repayment. This clarity stops you from assuming a low rate hides costly charges.
- Read the loan agreement in full before signing
- Highlight any variable rates or caps
- Note all fees and when they apply
- Plan payments to avoid defaults
Compare repayment schedules by calculating total cost over the term, not just monthly payments. Look for flexibility, such as payment holidays or if you can adjust the term without penalties.
Understanding your own credit helps you anticipate rates and approval odds, reducing frustration when applying.
- Identify all charges upfront
- Check the fine print on penalties
- Estimate total payoff over time
- Ask about flexible repayment options
Legal basics for lenders
Lenders must disclose key terms clearly and comply with consumer protection rules. If something feels opaque, ask for a plain-language summary before you proceed. This reduces disputes later.
Keep a record of all communications and changes to terms. Written proof helps if terms drift or a dispute arises.
Understand how late payments affect your credit and entry into collections; early intervention can prevent long-term damage.
- Document requests you make and their responses
- Know your rights if terms change
- Learn how credit reports reflect loans
- Seek neutral advice when terms feel biased
How to compare loan offers
Side-by-side comparisons
Create a simple table listing each lender’s rate, fees, term, and prepayment options. This makes differences obvious and actionable. Use a spreadsheet or a printable checklist to stay organized. A useful resource on this topic: Ankara Ceza Kovuşturması Avukatları.
Rank offers by total cost, not just the monthly payment. A lower payment can hide higher fees or longer terms.
Consider your cash flow: if your income is irregular, prefer fixed payments and a reasonable term to avoid stress.
Use a real scenario: if you miss a payment, what happens to your rate and penalties?
- Rate, fees, term, penalties
- Total cost comparison
- Cash-flow fit
- Penalty implications
Using a broker or platform
A broker can simplify options, but you still need to verify the terms yourself. Ensure the platform charges transparent fees and that recommendations match your goals.
Ask how the broker earns and whether any recommended products carry higher commissions. This transparency protects you from biased guidance.
Always compare the broker’s suggestions with direct lender quotes to confirm they’re competitive and appropriate for your situation.
Document all disclosures and confirmations for later reference.
- Check fee structures
- Verify recommendations against direct quotes
- Assess conflicts of interest
- Keep copies of all disclosures
Common pitfalls to avoid
Overlooking total cost
Focusing only on the monthly payment can mislead you about affordability. Add up all payments over the life of the loan to see the real burden.
- ☐ Calculate full loan cost before signing
- ☐ Be wary of teaser rates
- ☐ Question add-ons that raise price
- ☐ Choose essential features only
Look past introductory rates; many loans carry rising rates after a teaser period. Plan for a potential increase in payments.
Beware optional add-ons that inflate the loan cost without adding value.
- Total cost awareness
- Watch for rate resets
- Avoid unnecessary add-ons
| Option | Pros | Cons |
|---|---|---|
| Fixed-rate loan | Predictable payments | Lack of flexibility |
| Variable-rate loan | Potential savings | Uncertainty in rate |
| Credit-union loan | Strong member terms | Membership requirement |
Hidden fees and penalties
Some lenders hide charges in vague terms or require automatic payments to avoid fees. Read the conditions that trigger penalties and when they apply.
Check if there are early repayment penalties; paying off ahead of schedule can save money but may not be allowed.
Verify any service or maintenance charges that recur throughout the term.
- Read all penalty terms
- Know early payoff rules
- Identify recurring service fees
Revisit terms if your income changes; renegotiating with the lender can be possible in some cases.
Smart tips to manage loans
Develop a repayment plan
Create a realistic monthly budget that includes loan payments. Align debt payments with essential expenses to avoid missed payments.
- List all debts and minimum payments
- Prioritize highest-interest loans
- Automate payments to avoid misses
- Review yearly and adjust
Set milestones for paying down principal to reduce interest over time. This builds momentum and confidence.
Revisit terms if your income changes; renegotiating with the lender can be possible in some cases.
- Budget around payments
- Set principal-reduction goals
- Reassess if income shifts
When to seek legal help
If you face a disagreement over terms, a lawyer can interpret complex language and protect your rights. Early consultation can prevent costly mistakes.
Use targeted legal advice for contract reviews, not general counsel for routine inquiries. This keeps costs predictable.
Avukat Ara can help in clarifying jurisdictional issues, contract ambiguities, and debt collection practices that affect your finances.
- Get a contract review
- Ask about jurisdiction and rights
- Clarify debt collection terms
Legal remedies and options
Legal avenues for debt relief
When you face a loan default or hardship, legal avenues can provide structured relief. Start by documenting your income, expenses, and missed payments so a lawyer or advisor can assess options like renegotiation, consolidation, or temporary forbearance. This is about choosing a path that preserves credit while reducing monthly stress.
A licensed attorney or consumer rights advisor can explain which remedies fit your situation, including negotiation leverage and any potential court options. You’ll want to understand timelines, eligibility, and the likely impact on future borrowing.
Think of this step as a first yes-or-no check: are you eligible for practical relief without long-term penalties? Gather basic documents and set a clear goal for what relief looks like, whether lower payments or extended terms.
- Prepare a hardship statement with clear numbers
- Identify all lenders and account numbers
- Ask for formal written proposals from lenders
- Keep records of all communications
Investing around debt
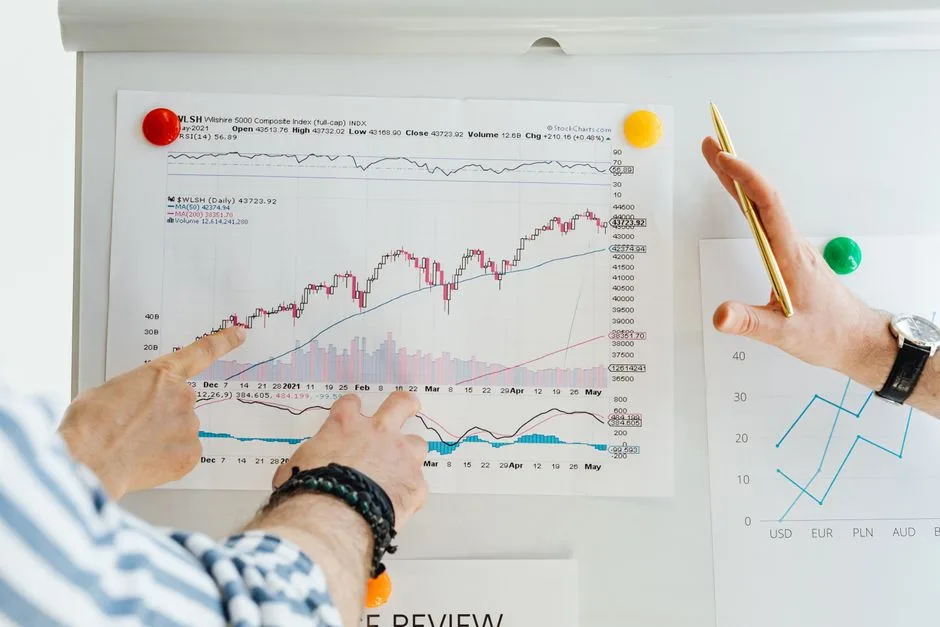
Balancing debt with growth goals
Debt can be kept as a tool if it supports growth or cash flow. For personal finance, prioritize high-interest debt but don’t neglect investment, especially where employer matches or tax-advantaged accounts exist. The aim is to keep debt costs under control while preserving investment momentum.
Consider allocating a modest portion of disposable income toward a low-risk, diversified fund while negotiating better rates on loans. This balance helps protect long-term goals without neglecting present obligations.
Create a simple plan: reduce the highest-rate debt first, then apply steady contributions to an emergency fund and a retirement account.
- Target high-interest balances first
- Lock in rate reductions where possible
- Automate monthly payments to avoid missed deadlines
- Review investment risk tolerance regularly
Digital tools for loan management
Apps and dashboards that help you track loans
Managing several loans can feel overwhelming; a centralized dashboard reduces that load. Use a reputable budgeting or loan-tracking app to monitor balances, due dates, and interest accrual. This makes late payments less likely and allows proactive negotiation with lenders.
- Set up one primary loan tracker
- Enable alerts for all due dates
- Link accounts only to trusted apps
- Run a monthly reconciliation
Experiment with color-coded categories and alerts for due dates. You’ll spot when a loan becomes expensive due to variable rates or fees and act before costs rise. Keep the data synced with statements for accuracy.
Establish a weekly moment to review the dashboard, not a quarterly sprint. Small, regular checks beat sporadic, high-effort reviews that miss changes in terms or charges.
- Choose reputable apps with strong security
- Set automatic reminders a week before due dates
- Export data for tax or credit reports
- Regularly reconcile app data with bank statements
Final checks before signing
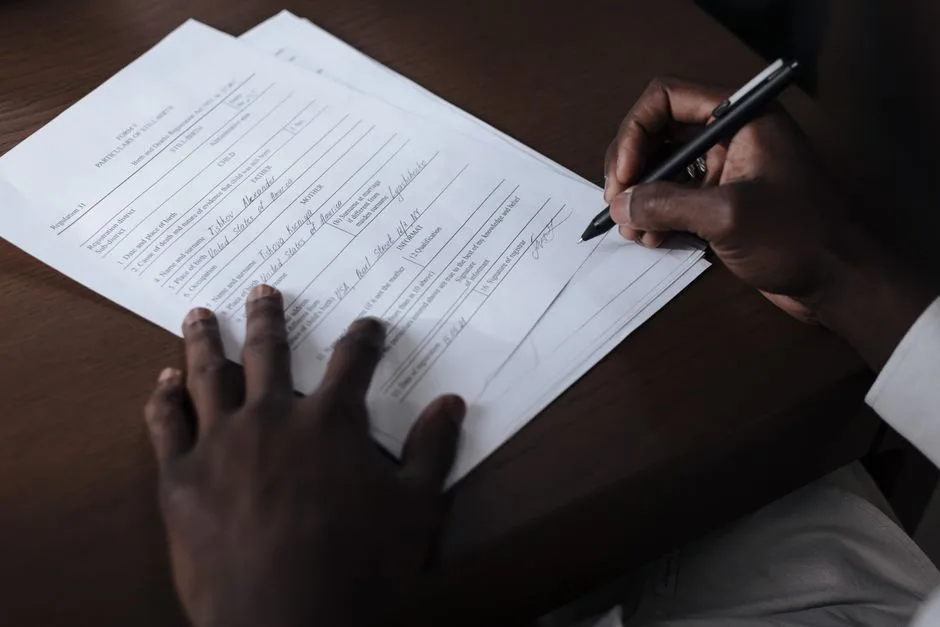
Reading the agreement carefully
Before signing any loan agreement, read every clause that defines fees, prepayment penalties, and default triggers. A straightforward contract should spell out payment schedules, total costs, and any consequences of late payments. If something feels ambiguous, pause and seek clarification.
Check the fine print for fees that are charged after you miss a payment or restructure terms. Look for hidden costs, such as annual fees or penalty interest that can dramatically increase the total you repay.
Bring a trusted advisor or lawyer to review the document; a second pair of eyes can catch unfavorable terms you might miss.
- Identify all charges and when they apply
- Confirm loan term and repayment schedule
- Verify how interest is calculated
- Ask for a clean, revised copy if any clause changes
Frequently asked questions
How do I choose between fixed and variable rates for a loan?
Fixed-rate loans provide predictable payments and shield you from rate swings, which is valuable in a stable budget. Variable rates can start lower but carry the risk of rising costs. Assess your tolerance for uncertainty and the likelihood of rate moves in your region; lean toward fixed if you plan to keep the loan long term.
What costs should I expect beyond the principal?
Look for origination fees, processing fees, late payment penalties, and any insurance or service charges. Some lenders bundle these into the APR, others itemize them separately. Add these to your total cost when comparing offers.
Can I still borrow with imperfect credit?
Yes, but terms may be stricter: higher rates, smaller loan amounts, or more collateral. Consider building credit by timely small payments or secured loans before pursuing larger borrowings. A careful approach reduces long-term costs.
How often should I review my loan portfolio?
Review at least quarterly, or after big life changes like a new job, relocation, or a major expense. Check for better offers, any misapplied payments, and opportunities to refinance or consolidate.
Next steps and ongoing care
Take the insights from these checks and apply them to at least one loan decision this month. Start by listing all active loans, their costs, and any upcoming due dates, then identify one area to improve, such as renegotiating a rate or batching payments.
Set a monthly routine: review statements, compare offers, and adjust your plan as needed. Use Avukat Ara as a resource for clarified legal questions tied to debt, contracts, and lender rights while keeping focus on your finances.